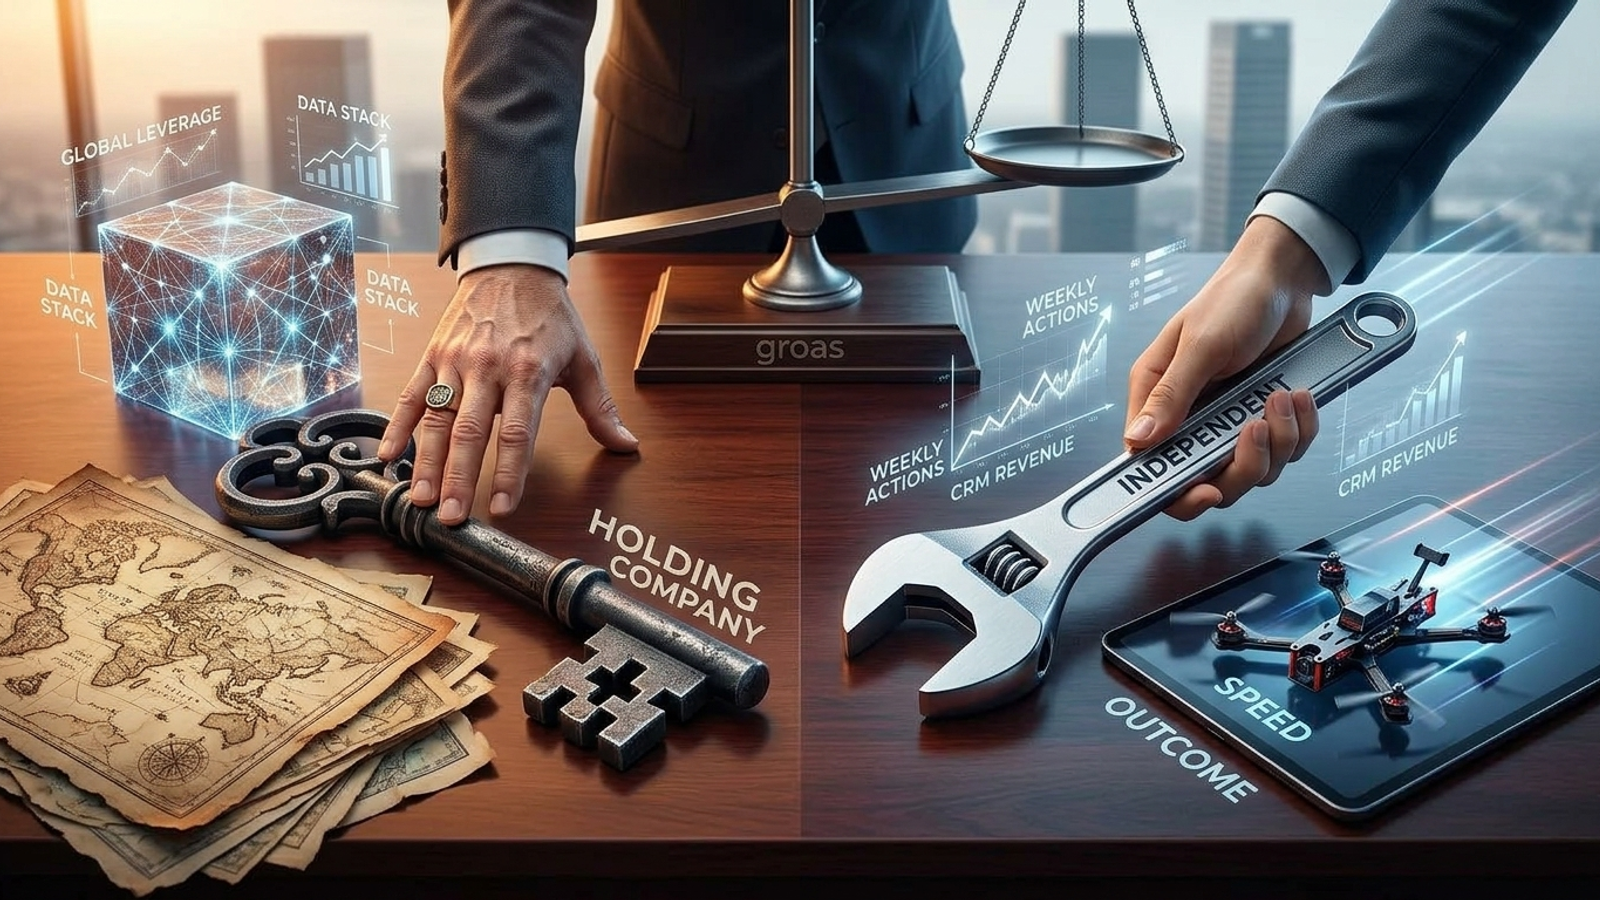
A seven-figure paid search account lands on two desks: Dentsu offers an enterprise network and deep data infrastructure; Tinuiti or Wpromote offers a tighter performance operation. Who should own the decisions that move that account every week? Smart buyers disagree because the holding company can absorb global complexity, while the independent promises faster execution closer to the people doing the work.
I think enterprise buyers frame this too broadly as scale versus speed. Google Ads auctions do not offer wholesale volume discounts: an algorithm calculating Target CPA does not care whether your agency network bills $2 billion or $20 million. The narrower question is whether the holding company’s leverage in other media and its data infrastructure outweigh a slower change cycle and reporting that can drift toward platform metrics.
I will argue each model at its strongest before calling it. The test is not whose pitch deck looks more expensive. It is who owns account decisions, how quickly those decisions become action, and whether anyone can show what search contributed to the business.
The case for Dentsu: scale can protect a complex business
The holding company model exists because a global business has problems that no brilliant search specialist can fix alone. When Dentsu unified its performance execution by folding Merkle’s media operations into iProspect, it assembled more than 600 dedicated search specialists managing north of $2 billion in annual search media. For a retailer running campaigns across forty territories, that bench is an institutional insurance policy. If an account director leaves on Tuesday, the work does not have to stop with that person. A smaller agency has a harder time absorbing the same departure.
Dentsu’s stronger argument is data. Browser privacy changes and signal decay have made standard tag-based analytics less dependable. Merkle’s Merkury identity platform is built to connect visitor identity with enterprise customer data. Linked with systems such as Google Cloud BigQuery, Salesforce Data Cloud, and GA360, that infrastructure gives a search team a route from offline CRM records to bidding signals. The point is to steer toward customer lifetime value and margin, not simply the largest pile of leads. A client with complicated databases may reasonably prefer established pipelines to building every connection itself.
Then there is the buying power that does matter. Upfront commitments in connected TV, retail media, and programmatic display can trade on aggregate spend even though Google Ads auctions do not. A brand spending $50 million across search, programmatic, and streaming may benefit from centralized negotiation. It may also value one set of agreements and compliance processes across subsidiaries more than it values shaving a day off a search change.
That is the best holding company case: you are buying organizational capacity, not cheaper search clicks. If governance, continuity, and cross-channel purchasing are your binding constraints, Dentsu has an answer an independent cannot easily reproduce.
The case for Tinuiti and Wpromote: decisions closer to the account
The independent’s best argument starts on an ordinary Thursday. Search terms shift, a product goes out of stock, or a campaign begins assigning too much value to the wrong conversions. The useful question is not how many specialists the agency employs worldwide. It is whether the people looking at the account can make a sound change before the weekend.
In a traditional holding company structure, changing ad copy or shifting budget between non-brand search and Performance Max can require several approvals and a revised media plan. Performance-focused independents such as Tinuiti and Wpromote make the opposite pitch: shorter operational loops and practitioners closer to the decision. If Google Ads is your main acquisition engine, an agency built to negotiate television upfronts may be more organization than you need. You need someone who can spot a search-term anomaly, work through its cause, and act while the finding is still useful.
Nor is this simply a contest between the holding company’s technology and the independent’s hustle. Tinuiti manages between $3 billion and $4 billion in media spend through its Mobius suite. MobiusOS brings platform signals together, Mobius Apps supports forecasting and media mix modeling, and MobiusX handles retail media activation. Its Bliss Point Media saturation models help retail teams assess where more spend begins to produce diminishing returns. Wpromote built Polaris on Google Cloud, drawing on more than 1,400 client data feeds across BigQuery and Looker. In multi-market enterprise pilots, Wpromote reported cutting manual reporting overhead by up to 93% and lifting lower-funnel ROAS by 29%. These are substantial operations, not two people and a dashboard.
The independent’s most persuasive promise is practitioner proximity. A seasoned strategist can impress everyone in the pitch, then vanish once the contract clears legal; that risk is not confined to holding companies. But an independent whose identity depends on performance has a stronger reason to keep the people making decisions close to the commercial outcome. Pipeline, customer acquisition cost, and attributable revenue should carry more weight than impressions or a handsome weekly report. Before you sign, find out whether that promise describes your actual account team.
Tinuiti or Wpromote? The account type decides
Tinuiti’s search proposition is particularly relevant to a catalog-driven retailer. If you sell across Shopify, Amazon, Target, and wholesale, coordination between search activity and marketplace inventory matters. MobiusX is built around that retail environment, while the Bliss Point Media models address diminishing returns across search and retail media. The question to press in the pitch is account tiering. Industry analyses raise the concern that brands spending $1 million to $5 million a year may receive a different level of senior attention from the largest accounts. Ask who will run yours. I covered that vetting problem in a comparison of Tinuiti with alternative management models.
Wpromote’s sharper fit is a pipeline-driven business with fragmented lead data. Polaris, built on BigQuery and Looker, addresses the work of bringing conversion feeds together. Its pairing of data and creative workflows is relevant when landing pages and ad copy need to reflect different kinds of search intent. Here, I would press on execution frequency. A Looker dashboard ingesting 1,400 feeds can make an excellent RFP slide. A dashboard does not make the bidding decision. If the search team discusses its findings only in a weekly sprint review, the account still runs on a weekly human clock.
Between the two, I would examine the shape of the search program before the agency logo. Catalog and inventory complexity points toward Tinuiti; lead scoring and first-party data plumbing point toward Wpromote. That is the independent case at full strength. Now for the problem neither pitch resolves on its own.
The rebuttal: a better stack can still measure the wrong win
The most damaging weakness across both models is the attribution shell game. Dentsu’s Merkury, Tinuiti’s Mobius, and Wpromote’s Polaris each give a pitch a serious measurement vocabulary. But a seven-figure advertiser needs to know whether Google Ads drove net-new revenue or intercepted someone already on the way to buy. A sophisticated stack does not answer that question just by producing a more detailed platform-reported ROAS figure.
Performance Max can take credit for high-intent brand searches and existing-customer queries. Paid media can also claim pipeline influenced by organic visibility, word of mouth, or field sales. Those risks matter because a team rewarded for gross spend or gross ROAS has little reason to go looking for redundant budget. I explored the incentive in this critique of holding company Google Ads management. The practical demand is straightforward: show incremental business outcomes, not just platform credit.
Holding companies face another conflict when they buy media inventory as a principal and resell it to clients. The Media Leader described industry disputes over transparency around that practice. A survey of advertisers found that 56% expected to encounter principal-based buying, while 90% considered reselling agency-owned inventory a conflict of interest. If an agency earns more when budget moves into inventory it controls, its cross-channel recommendation deserves scrutiny. Independents may avoid that particular arrangement, but a percentage-of-spend fee creates its own friction: cutting waste can cut the agency’s billings.
The last shared weakness is pacing. The auction keeps moving during a weekly status call. If a competitor’s promotion changes the economics over a weekend, an approval chain that takes days costs money; an independent that responds faster still depends on someone noticing, deciding, and acting. I have spent enough time in accounts to respect the judgment involved. I have also spent enough time mining negatives to know that not every repetitive decision needs a meeting.
This is where the familiar debate between a giant and a nimble shop gets too comfortable. Faster human review is still human review. For an enterprise buyer, the issue is not merely which agency moves faster. It is whether the operating model connects continuous account action to a defensible account of revenue across channels.
Put the decision test in the RFP
Before I give either side the account, I want answers that survive contact with the actual team and contract. Ask these questions in the RFP, not after three months of polished reports:
- Where does buying power help you? If the media mix depends on negotiated upfronts across broadcast, streaming, and retail media, ask the holding company to explain the advantage for your plan. If most of the budget runs through Google Ads auctions, do not accept aggregate network billings as a search-pricing argument.
- Who owns a decision on Tuesday? Name the people who can change budgets, search structure, negatives, and conversion value rules. Ask what requires client approval and how long that process takes. Seniority on the pitch team is not an answer.
- What does your data infrastructure already do? If first-party data, a warehouse, and CRM connections are in place, ask what the proposed identity or intelligence stack adds. If those connections are missing, ask who will build and maintain them.
- How will you test incremental value? Require a plan for geo-split experiments or branded search holdouts rather than relying on platform ROAS as the primary proof of success. Tie the discussion to qualified pipeline, closed-won revenue, and customer acquisition cost.
- What can you audit? Require access to Google Ads change history and clear terms for media markups and principal-purchased inventory. Ask how compensation behaves when the right recommendation is to spend less.
None of this requires an agency to promise that every campaign will work. It requires the people taking responsibility for the account to make their decisions and incentives visible. If a team cannot explain who acts, when, and on what evidence, I would not let its slide about transformation decide a seven-figure budget.
My ruling: buy cross-channel accountability, not a logo
For a global conglomerate whose search account is one part of large TV, streaming, and retail media commitments across many markets, I would choose Dentsu. The governing problem there is coordination: enterprise data connections, compliance, continuity, and negotiated media relationships. Search speed matters, but it does not outrank the machinery needed to run the whole operation.
For an enterprise brand whose primary commercial engine is paid search, I would take the independent over the holding company. Tinuiti is the stronger agency fit when the work revolves around retail feeds and inventory; Wpromote is the stronger fit when it revolves around lead data and creative coordination. In either case, I would verify who touches the account and how often. Neither a catalog tool nor a data pipeline earns its keep while the decision waits in a queue.
But I would not stop the RFP at those three logos. The single consideration that decides it for me is cross-channel accountability: can the operating model act on search continuously while proving that paid and organic visibility produced attributable business outcomes rather than competing to claim the same sale? Agency teams can be excellent at parts of that job. Their scheduled reviews and spend-based incentives are still a poor default for the whole thing.
That is why we built groas as a fully autonomous growth engine for paid and organic search. Purpose-built models execute bidding, keyword discovery, negative filtering, and intent-matched landing page work continuously, while a named human strategist owns direction, guardrails, and accountability. I would choose that model for a search-led enterprise buyer before paying for another layer of agency hours around work the machines can do. The strategist still has to answer the hard question: what revenue did those decisions actually help create? That is the question I would put at the top of the RFP.